
BTE Newsletter #49: À-La-Carte, or All-In-One?
Good morning everyone, and Happy Tuesday Wednesday. I hope you all had a great Thanksgiving weekend. Mine was quite nice, since I spent part of it watching the Ravens win a thriller with their backup quarterback.
More importantly, last week I had the pleasure of attending two conferences, both on Tuesday. One was the LP Tech Summit, which focused on the back-end plumbing for institutional investors, as it relates to Private Markets. The other was run by Boston-based HarbourVest Partners, a firm I’ve long admired despite having so many Patriots fans.
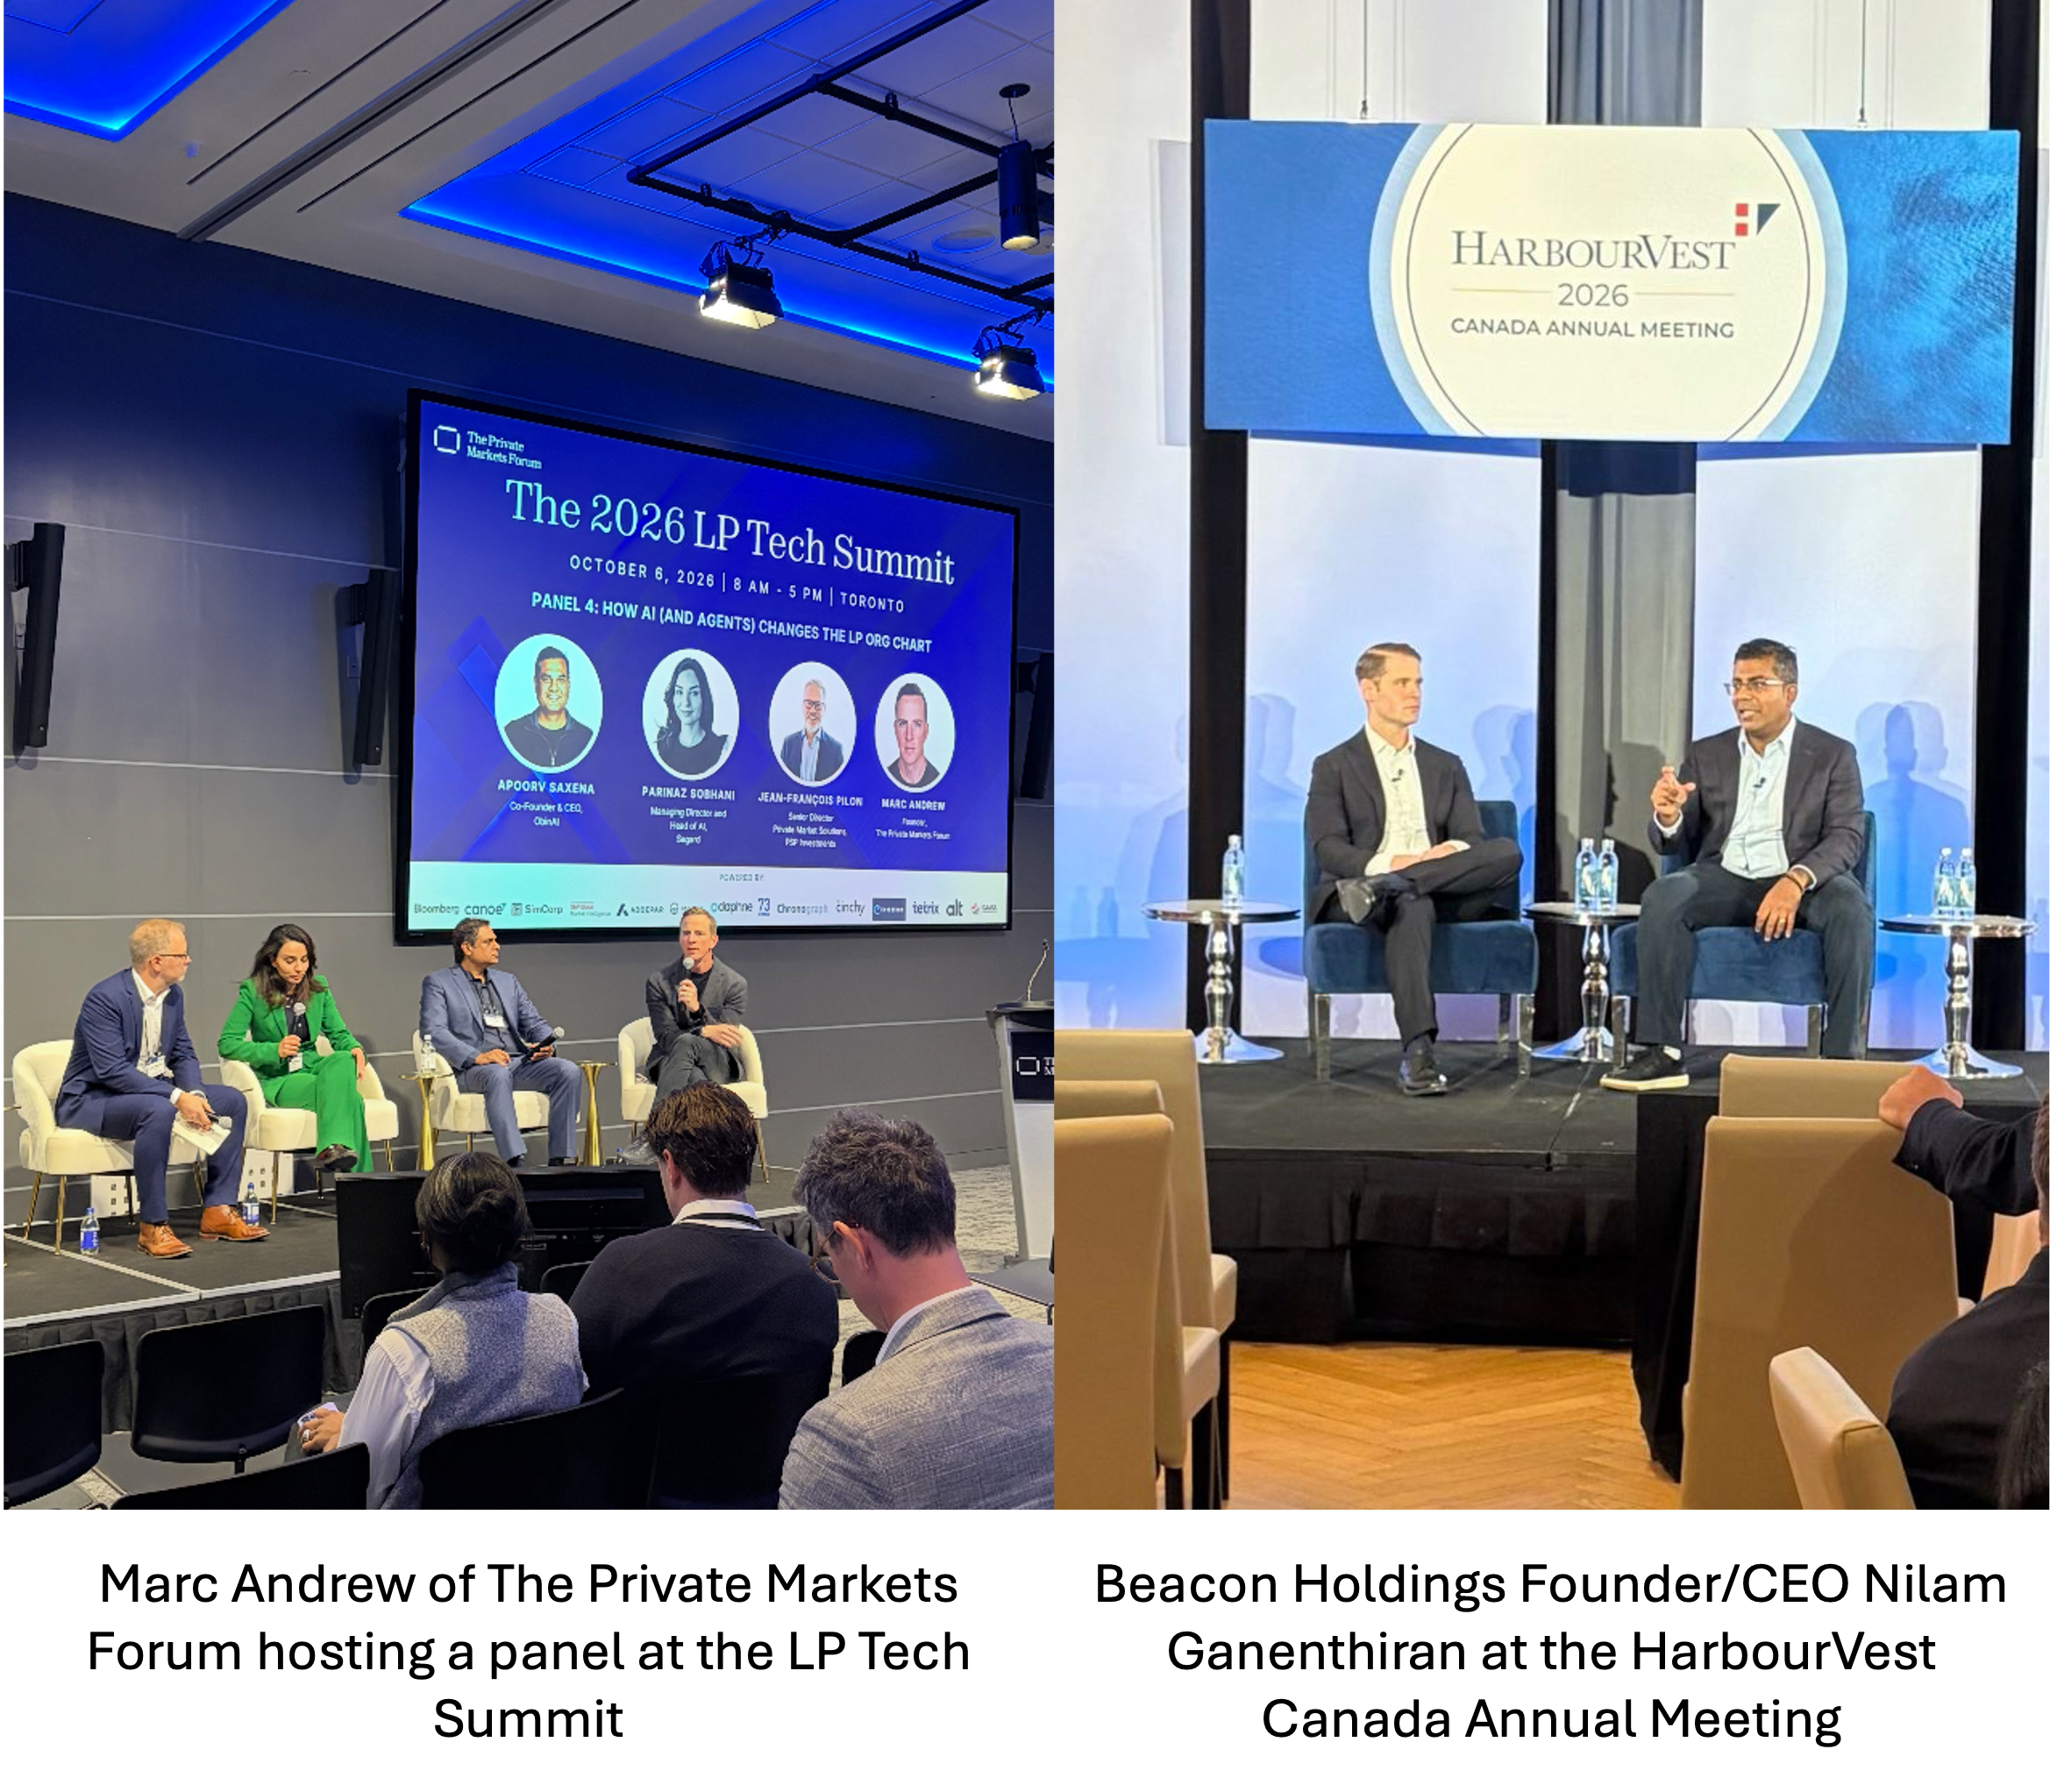
In other news, I hope to have the next podcast episode released by this weekend. So now you can hold me accountable to it. I also plan on attending some more events (I suppose it’s that time of year) hosted by AGF, Partners Group, Blue Owl, and finally the Alts X Alts conference in early November. To those of you going to any of these events, I’ll see you there.
As for this week’s newsletter, there have been quite a few announcements of “All In One” Private Markets products that combine various underlying strategies. The latest was the launch of the “Blackstone Private Markets Fund”, which combines the firm’s Equity, Credit, Real Estate and Infrastructure strategies. So I’m overdue for a newsletter issue discussing this subject.
Ben
What To Make of “All In One” Private Markets Funds
When it comes to investing in public markets, some financial advisors prefer to pick individual securities. But this is not as common as it once was. Outperformance versus public indices has become more difficult (if not impossible), and clients have come to expect more from their advisor on the planning side.
So naturally, strategies have evolved that allow advisors to invest money for their clients, and build diversified public market portfolios, but without the same effort or cost. These strategies include:
Mutual funds in their current form date back more than 100 years, with the first such product being created in 1924. And while they are traditionally a relatively expensive option, they are gradually becoming more cost-effective.
Index funds, which allow investors to invest passively, are 50 years old this year after Vanguard introduced the product in 1976.
Exchange-traded funds date back to 1990, and were first launched by the Toronto Stock Exchange. In the United States, there are now more ETFs than stocks.
Fund-of-funds make it easier to get instant diversification across one or more asset classes.
Model portfolios at a wealth management firm can give advisors a set of investments to replicate, while also allowing for more flexibility at the advisor level.
It’s not so easy in the Private Markets
In the Private Markets, it’s a very different story. Without the presence of financial exchanges, transparent data, comprehensive databases, or consistent standards, it can be difficult (or even impossible) to get instant diversification or invest passively. Consider the following:
Evergreen funds can be thought of loosely as mutual funds for Private Markets, but there are various nuances, including much less transparency and liquidity. There are also big gaps between the best and worst performers, much more-so than in public markets.
There are no investable indices for Private Markets, particularly for individual investors.
Without investable indices or financial exchanges, an indexing approach is impossible for Private Markets. ETFs do exist that look to replicate Private Market strategies, but they use public securities to do so (this was the subject of one of my podcast episodes, with Julian Klymochko of Accelerate Financial Technologies).
There is no comprehensive database for Evergreen funds in Canada, although some are working on the idea, as I talked about in newsletter issue #47.
So that leaves an obvious question. Suppose an advisor focuses primarily on planning and other services, while taking a passive approach to investment management. Now suppose that advisor has no experience with Private Markets, but also concludes that something must be done. The advisor is facing a slew of hurdles, such as a variety of private asset classes to consider, a lack of available information, and considerable know-your-product requirements. What should the advisor do? Or put another way, where should the advisor even start?
This isn’t a trivial question, and it’s one that I’ve been asked many times this year by such advisors. One advisor even told me point blank: “the due diligence would kill me.”
At times I’ve given other advisors a list of my favourite funds, but that’s not especially helpful, since that list can change over time. And those advisors are still required to do their own due diligence. So instead, the most practical approach is usually a fund-of-funds.
Fund-Of-Funds in Private Markets
When investing in Private Markets, fund-of-funds offer a number of advantages, including:
Due diligence is effectively outsourced to dedicated Private Markets specialists.
There is only one subscription document for a fund that covers multiple strategies, which is especially helpful when end clients have to sign subscription documents as well.
Diversification can help manage illiquidity. If one underlying holding in a fund-of-funds restricts withdrawals, other holdings may still provide liquidity to meet redemptions. By comparison, investing directly in a single Private Markets fund leaves the entire investment subject to that fund’s redemption restrictions.
In Canada, a number of firms offer fund-of-funds in the Private Markets. Four in particular are worth highlighting (three of which have already appeared on my podcast):
Westcourt Capital: Founded in 2009 by David Kaufman, the firm specializes in building alternative investment portfolios for high net-worth individuals and institutional clients. Its fund-of-funds offering is the “Westcourt Performance Portfolio” (WPP), which combines Private Equity, Real Assets, Real Estate, Credit, and Absolute Return strategies.
Trans-Canada Capital: Born out of the Air Canada pension plan, TCC aims to bring its institutional investing approach to individuals through the “TCC Alternative Access Fund”, which combines Private Equity, Credit, Real Estate and Infrastructure strategies. I recently interviewed David Alloune from TCC for episode 14 of the podcast.
Obsiido: Launched in 2023, Obsiido offers two fund-of-funds, one focused on growth and the other on income. I interviewed their Chief Investment Officer Sean O’Hara for episode 2 the podcast.
Bridgeport Asset Management: A wealth manager founded in 2007 by John Fisher, Bridgeport was one of the early adopters of alternative investing strategies, before they became more broadly available. Bridgeport has opened up its strategies to other firms, offering eight different funds, including four in the Private Markets space. I interviewed John for episode 4 of the podcast.
Other Strategies
Besides fund-of-funds from independent firms, there are other ways firms are looking to solve this problem that financial advisors are facing.
For instance, some funds combine different strategies from the same firm. I already mentioned Blackstone’s announcement. Meanwhile Partners Group has a similar fund, which is distributed in Canada by BMO. For advisors that are very comfortable with one firm in particular, this may be the best way to get Private Markets exposure.
Other products aim to combine public and private strategies. Capital Group and KKR have a close partnership to offer such funds. Similar funds have been launched through a partnership between Wellington, Vanguard and Blackstone. Apollo has been working with State Street to provide ETFs combining public and private credit. Other firms have been combining public and private strategies through model portfolios, including Partners Group and BlackRock.
Conclusion: These Products Have Their Place
The fund-of-funds and other all-in-one strategies are not a perfect solution for Private Markets allocations. Different clients have different risk tolerance levels, income requirements, and tax profiles, and an à-la-carte approach allows an advisor to be more adaptive to these needs. For instance, growth-oriented investors may be better served by Private Equity, those needing income may veer towards Private Credit, and people seeking tax-efficient diversification may go for Real Estate or Infrastructure. All-in-one products take away some of that flexibility.
That being the case, most financial advisors have little interest in selecting their 2-4 favourite funds in Private Equity, Private Credit, Private Real Estate, and Private Infrastructure. Especially not if their schedule (and expertise) is already devoted towards financial planning, client servicing, business prospecting, and public markets.
For that very reason, I’d expect the use of all-in-one strategies to grow significantly, and for many more such products to enter the market.
Want to find out more?
Private markets are not for everyone, and come with a number of risks, such as higher illiquidity and less transparency.
However, many of the world’s leading institutions and wealthiest families put a big emphasis on private markets, and recently these strategies have become more available to individuals too. Drawing on my background as an analyst specializing in private markets, I help investors cut through the complexity and understand how to build portfolios incorporating these strategies.
To explore whether these strategies are suitable for you, please schedule a 30-minute virtual meeting below:
Disclaimer
Benjamin Sinclair is a representative of Designed Securities Ltd. Designed Securities Ltd. is regulated by the Canadian Investment Regulatory Organization (ciro.ca) and is a Member of the Canadian Investor Protection Fund (cipf.ca). Investment products are provided by Designed Securities Ltd. and include, but are not limited to, mutual funds, stocks, and bonds. Benjamin Sinclair is registered to provide advice and solutions to clients residing in the province of Ontario. For more information, please see www.beyondtheexchange.ca/disclaimer/